The New Tips Deduction: A Guide for North Carolina Service Workers and Business Owners
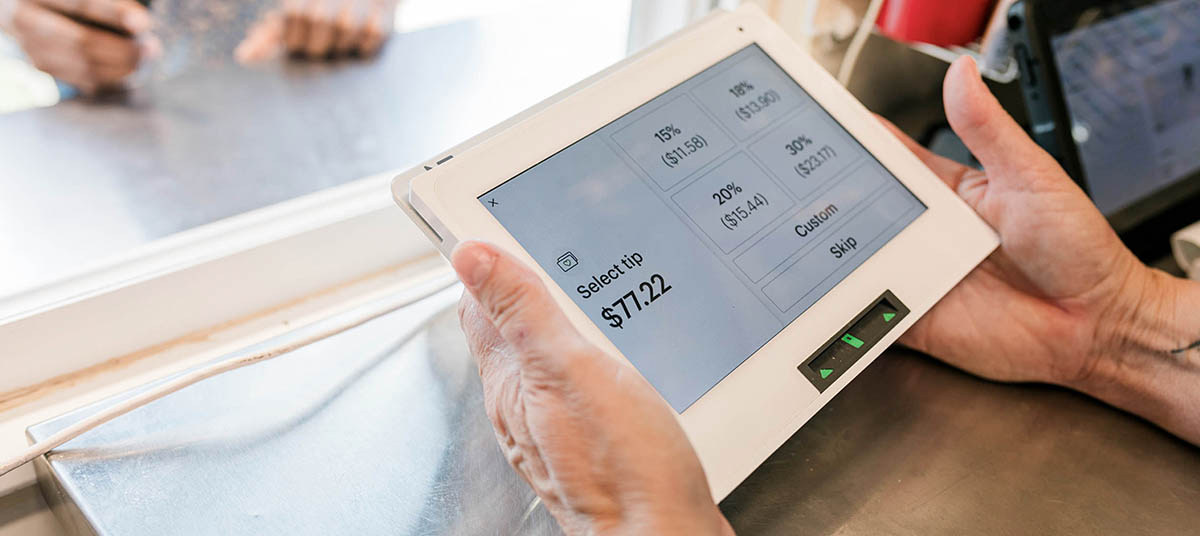
A new federal tax break for tip-earning professionals has arrived, effective for tax years 2025 through 2028. This temporary provision introduces a ‐below-the-line‐ deduction for ‐qualified tips,‐ offering a significant opportunity for service workers and gig entrepreneurs to lower their tax liability. However, the IRS has established specific eligibility criteria and strict reporting standards that taxpayers must follow to secure these savings.
At Bly Business Accounting, we focus on making complex tax changes simple for North Carolina’s small business owners and service professionals. Understanding the nuances of this deduction—from occupation codes to annual caps—is essential to ensure you are not overpaying Uncle Sam or inviting an unnecessary audit. This guide breaks down the framework of the new tips deduction and what you need to do to stay compliant.
Understanding the Below-the-Line Deduction
In tax terminology, a ‐below-the-line‐ deduction is one that reduces your taxable income but does not impact your Adjusted Gross Income (AGI). For those earning tips in West End or across the state, this is a major benefit because it is available regardless of whether you choose the standard deduction or itemize your deductions on Schedule A. It effectively lowers the amount of income subject to tax without requiring you to forego other common tax benefits.
Eligibility Requirements for Tip Earners
To qualify for this deduction, you must meet several specific criteria. First, your occupation must be one that ‐customarily and regularly‐ received tips as of December 31, 2024. The IRS uses Treasury Tipped Occupation Codes (TTOCs) to identify these roles, covering approximately 200 different job types ranging from hospitality to personal services. Beyond your job title, you must also:
- Receive tips that meet the legal definition of ‐qualified tips.‐
- File a joint return if you are married.
- Possess a valid work-eligible Social Security number (SSN).
Annual Limits and Income Phaseouts
While the deduction is a welcome relief, it is not unlimited. The maximum amount any taxpayer can deduct is $25,000 annually. This cap remains the same whether you file as a single individual or a married couple filing jointly. If you are a high-earning service professional, it is important to track your total tips to see how close you come to this threshold.
The Modified AGI Phaseout
The deduction also includes a phaseout mechanism based on your Modified Adjusted Gross Income (MAGI). The benefit begins to diminish once your MAGI exceeds $150,000 for single filers or $300,000 for those filing jointly. Specifically, the deduction is reduced by $100 for every $1,000 (or fraction thereof) over these limits. For professionals in dual-income households, careful planning is necessary to ensure you don’t lose the deduction due to hitting these income ceilings.
Defining Qualified Tips Under Final Regulations
The IRS final regulations clarify exactly what counts as a ‐qualified tip.‐ This includes traditional cash, but also tips received via electronic payments, credit/debit cards, gift cards, and even casino chips. Voluntary tip pools also qualify, provided the distribution is properly reported. For managers and supervisors, tips only qualify if they were received for services the manager personally performed in an eligible tipped role.
What Is Excluded from the Deduction?
It is equally important to know what does not count. The following are specifically excluded:
- Digital Assets: Tips received in cryptocurrency, such as Bitcoin or stablecoins, are not considered ‐cash tips‐ for this deduction.
- Service Charges: Mandatory auto-gratuities or service charges are treated as wages, not tips.
- Owner Tips: Tips paid to individuals with a 5% or greater ownership stake in the business are ineligible.
- Illegal Activities: Tips earned in businesses that are illegal under federal law (such as the cannabis industry) cannot be deducted.
New Reporting Standards and 2025 Transition Relief
The documentation requirements for this deduction are becoming more stringent. Starting in 2026, the IRS will generally only allow the deduction for tips that appear on formal information statements like Form W-2 or various 1099s. This means that ‐under the table‐ cash tips that aren’t reported to your employer or payer will likely be ineligible for the deduction in the future, even though they remain taxable income.
The 2025 Transition Year
For the 2025 tax year, the IRS has provided a ‐transition relief‐ period. Since many employers and gig platforms haven’t updated their systems yet, self-employed taxpayers and contractors can rely on their own daily logs and receipts to substantiate their tips. However, beginning in 2026, employers will be required to use specific codes (such as code TP in Box 12 of the W-2) to identify tipped income for the IRS.
Special Considerations for the Self-Employed
For independent contractors and gig workers in North Carolina, the rules for the tips deduction are slightly more complex. Your deduction is limited to the lesser of the $25,000 cap or your net income from the business. Net income for this purpose is your Schedule C profit minus certain above-the-line adjustments like the deductible portion of self-employment tax and health insurance premiums.
Self-employed individuals must claim the deduction on Form 1040 Schedule 1-A rather than directly on Schedule C. It is critical to remember that this deduction cannot be used to create or increase a business loss. If your business isn’t profitable before the deduction, you won’t be able to utilize this specific tax break.
Practical Examples of the Tips Deduction
To see how these rules apply in the real world, consider these scenarios:
- The Annual Cap: A bartender earning $40,000 in tips in 2026 will see their deduction capped at $25,000.
- The Phaseout: A single filer with $160,500 in MAGI is $10,500 over the threshold. Since the deduction drops by $100 for every $1,000 (or fraction) over the limit, their deduction is reduced by $1,100, leaving them with a $23,900 deduction.
- Net Income Limit: A gig driver with $20,000 in net income and $1,413 in deductible self-employment tax is limited to a tip deduction of $18,587, regardless of how many tips they actually earned.
Proactive Tax Planning for Tipped Income
The new tips deduction offers a rare opportunity for service professionals to keep more of their hard-earned money, but the window is temporary and the rules are technical. Success starts with meticulous recordkeeping today so that you are prepared for the more rigid reporting requirements coming in 2026. Whether you are an employee or a small business owner, navigating these changes requires a clear strategy to maximize your savings while staying within the legal guardrails.
If you have questions about how these final regulations impact your specific situation or need help cleaning up your books to prepare for 2025, Bly Business Accounting is here to help. Schedule a consultation with our West End office today to ensure your financial future is on the right track.
Want tax & accounting tips and insights?
Sign up for our newsletter.